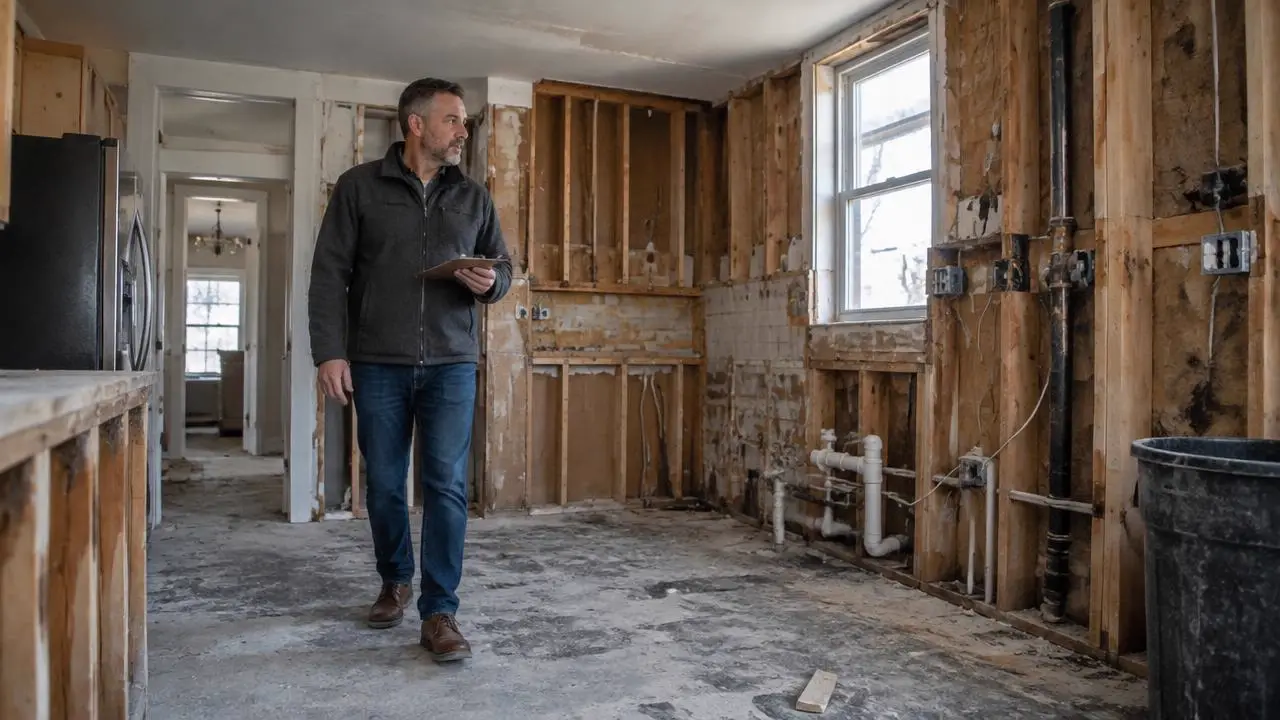
Quick answer: Off-market properties for sale are homes sold without an MLS listing, usually as-is, through wholesalers, direct-to-seller marketing or private buyer networks. Expect a 21-day close, cash or hard money, and no inspection contingency. On DispoKey, team-approved buyers see off-market Fix & Flip and Buy & Hold deals by city.
Off-market deals are where many investors find their margin, but they also come without the protections of a retail purchase. This guide explains where these properties come from, how to evaluate them quickly, and how to position yourself so good deals reach you first.
Where off-market deals come from
- Wholesalers who contract with motivated sellers and assign the contract to a buyer.
- Direct-to-seller marketing: mail, driving for dollars, search ads.
- Agents with pocket listings whose sellers want privacy.
- Estates, landlords and lenders wanting a fast, quiet sale.
- Vetted marketplaces that pre-screen deals and buyers.
Why sellers choose off-market
Sellers trade some price for speed, certainty and privacy. Inherited homes, tired landlords, and houses needing major repairs are common. That's why many off-market homes need work, and why your underwriting must be stronger than on a retail purchase.
How to evaluate an off-market deal
| Check | Fix & Flip focus | Buy & Hold focus |
|---|---|---|
| Value | ARV from closed comps | Current value + ARV for refinance |
| Income | Not applicable | Market rent; compare HUD Fair Market Rents |
| Repairs | Full rehab scope + contingency | Rent-ready scope + capex reserve |
| Costs | Financing, holding, selling | Taxes, insurance, vacancy, management |
| Exit | Retail resale price and buyer pool | Cash flow and refinance at appraisal |
| Diligence | Walkthrough, title, permits, flood | Same, plus lease and tenant status |
Example: a flip (labeled numbers)
ARV $250,000; rehab $38,000; financing, holding and selling $36,000; target profit $30,000. Maximum price ≈ $250,000 − $38,000 − $36,000 − $30,000 = $146,000. See how to analyze fix and flip deals for the full method.
Example: a rental (labeled numbers)
Rent $1,600; taxes, insurance, vacancy (8%), repairs (8%), management (10%) and capex reserves total about $720 per month. Net operating income ≈ $880 per month or $10,560 per year. At a price of $130,000 all-in, that's roughly an 8.1% cap rate before financing. Check local rents against HUD Fair Market Rents and recent listings.
Due diligence without contingencies
Most off-market deals don't allow inspection contingencies, and DispoKey marketplace offers are not inspection-contingent. Do the work first:
- Walk the property, with a contractor when possible.
- Review title for liens, judgments and open permits.
- Confirm zoning, code violations and flood zone.
- Confirm occupancy and leases on rentals.
- Line up financing before you offer.
How to get first look at deals
- Define a precise buy box: ZIPs, property types, price band, rehab tolerance, strategy.
- Have proof of funds ready.
- Respond quickly and close when you say you will.
- Give honest feedback on deals you pass on.
On DispoKey, you apply once with your buy box; our team reviews every application before granting marketplace access, and approved buyers receive credentials by call or email. Browse deals by market on our buyer city pages.
How to vet the person sending you the deal
The source matters as much as the property. Ask whether they hold a signed contract with the owner. Ask for the contract's closing date and whether it allows assignment. Check that the seller named on the contract matches the owner of record in county assessor data. Confirm that earnest money will be held by a title company, never wired to an individual. And treat emailed wire instructions with suspicion: wire fraud is common in real estate, so always call the title company at a number you find independently.
Public market data worth checking before you buy
Three free public datasets help you sanity-check a market. FHFA's House Price Index shows the direction of home values by metro. HUD Fair Market Rents give a baseline for local rents, useful for Buy & Hold deals. The Census Bureau's American Community Survey shows household income, owner versus renter share and vacancy by ZIP or tract, which helps you judge tenant demand and the pool of resale buyers. None replaces local comps, but together they flag markets where the story you're being sold doesn't match the data.
Buying an occupied off-market property
Many off-market houses come with an occupant: the seller, a family member or a tenant. Ask for the lease, rent roll and deposit amounts on any tenant-occupied home, and read your state's landlord-tenant law on how existing leases transfer to a new owner. For Fix & Flip, budget the time it may take for the home to become vacant. For Buy & Hold, an existing paying tenant can be an advantage if the lease rate is close to market. Never assume a vacant delivery unless it is written into the contract. If the seller still lives there, agree on a move-out date and any post-closing occupancy terms in writing before closing.
Financing an off-market purchase
Because closings are fast, most buyers use cash, a hard money or private loan, or a business line of credit. Get your lender's pre-approval for the property type and confirm their closing timeline before offering. Buy & Hold investors often plan a refinance after rehab; confirm the lender's seasoning rules first, since some require six months of ownership before using the new appraised value.
When off-market may not be your best option
If you need inspection or financing contingencies, can't walk properties yourself, or want a move-in-ready home, a retail MLS purchase is a better fit. Off-market rewards investors who move quickly, verify everything themselves, and carry risk knowingly.
Key takeaways
- Off-market homes sell as-is, fast, and without MLS exposure.
- Underwrite harder: verify ARV, rents and repairs yourself.
- Complete diligence before offering; expect no inspection contingency.
- A clear buy box and proof of funds get you first look.
- Fix & Flip and Buy & Hold need different checks.
Ready to see deals in your area? Apply for marketplace access. Related: analyzing fix and flip deals.
Related reading
- Vacant Property Insurance: Before-Closing Checklist
- Rental property cash flow analysis
- Buying tenant-occupied property
- How to estimate rehab costs
- Compare rent-to-value ratios in the 100 largest counties
- How to buy tax lien properties at county sales
- How to Calculate Cap Rate: Verify Rental NOI
- How to Buy a House at Auction: Investor Steps