
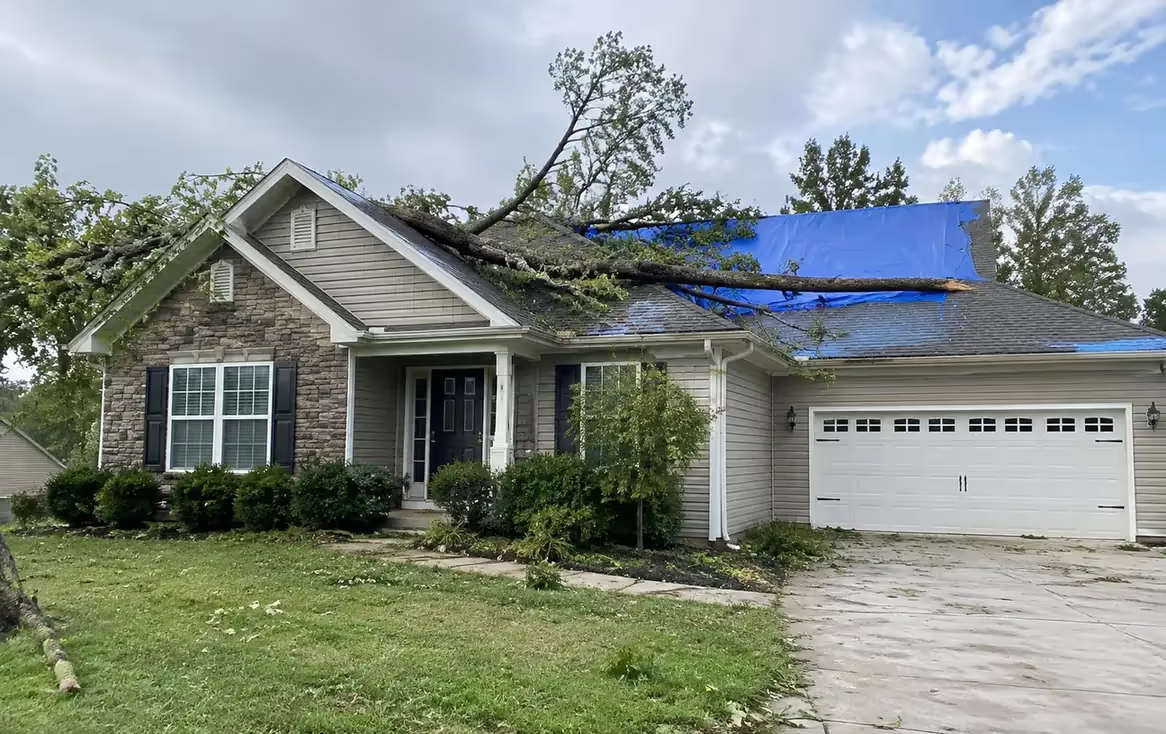
Fire, storm or water damage? Sell it as it stands
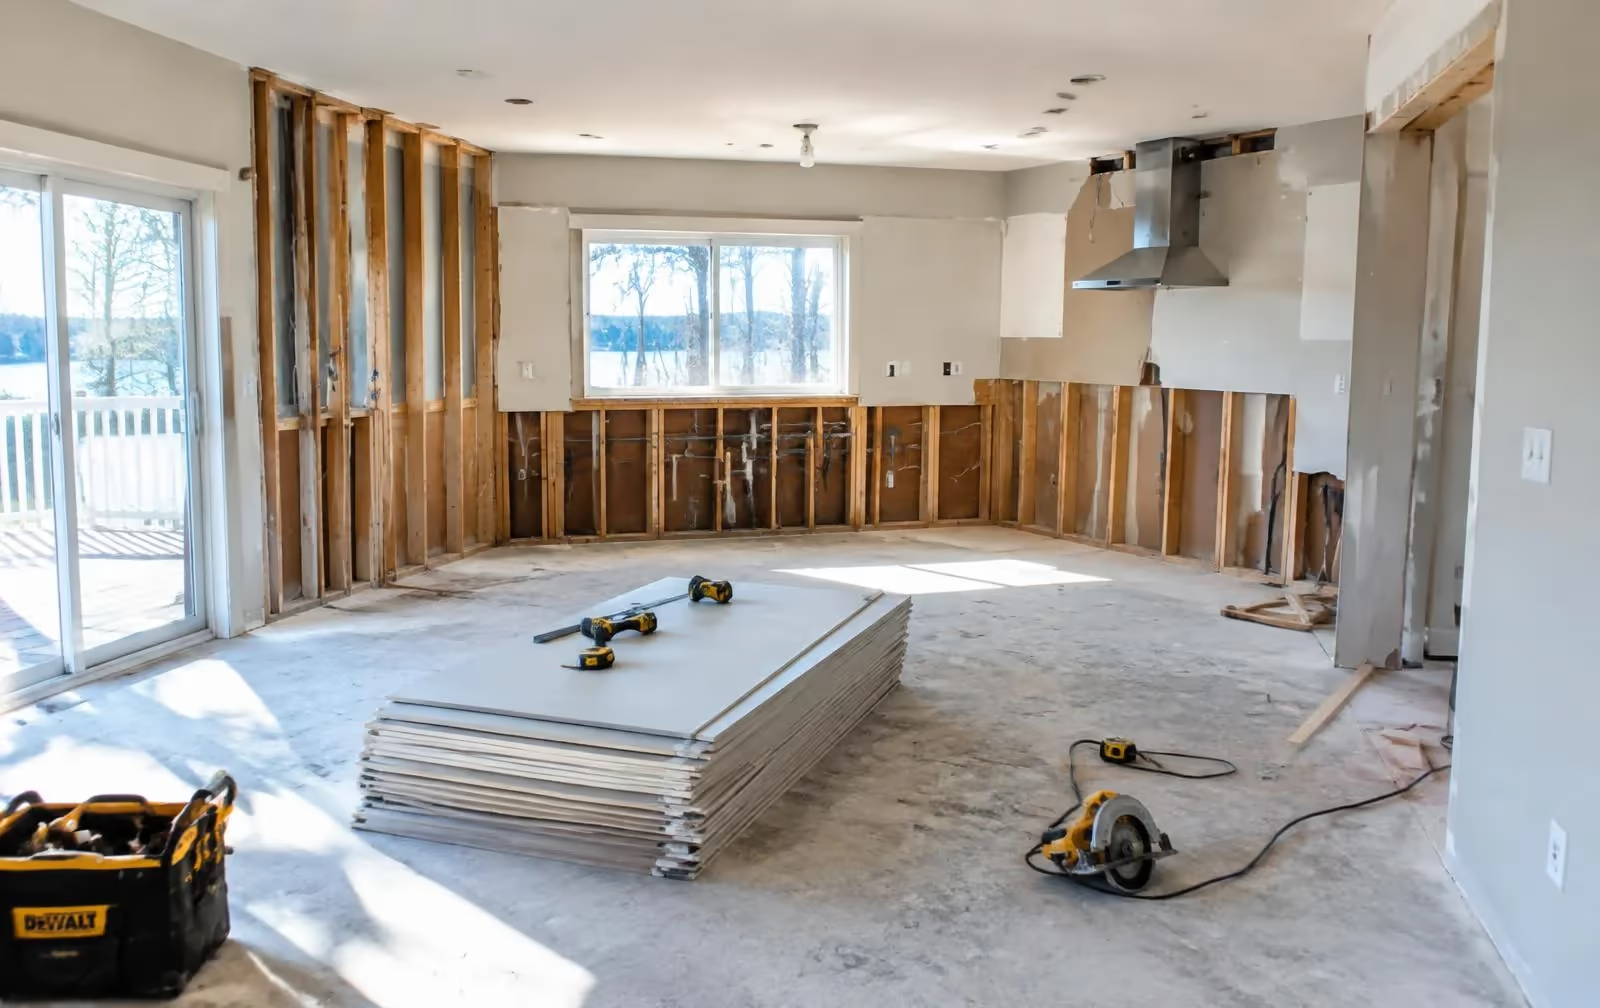
When the insurance check doesn't cover the rebuild, or you simply don't want to go through it, we buy the house in its damaged condition.
- No repairs or cleaning
- No agent commissions
- Funds held by title
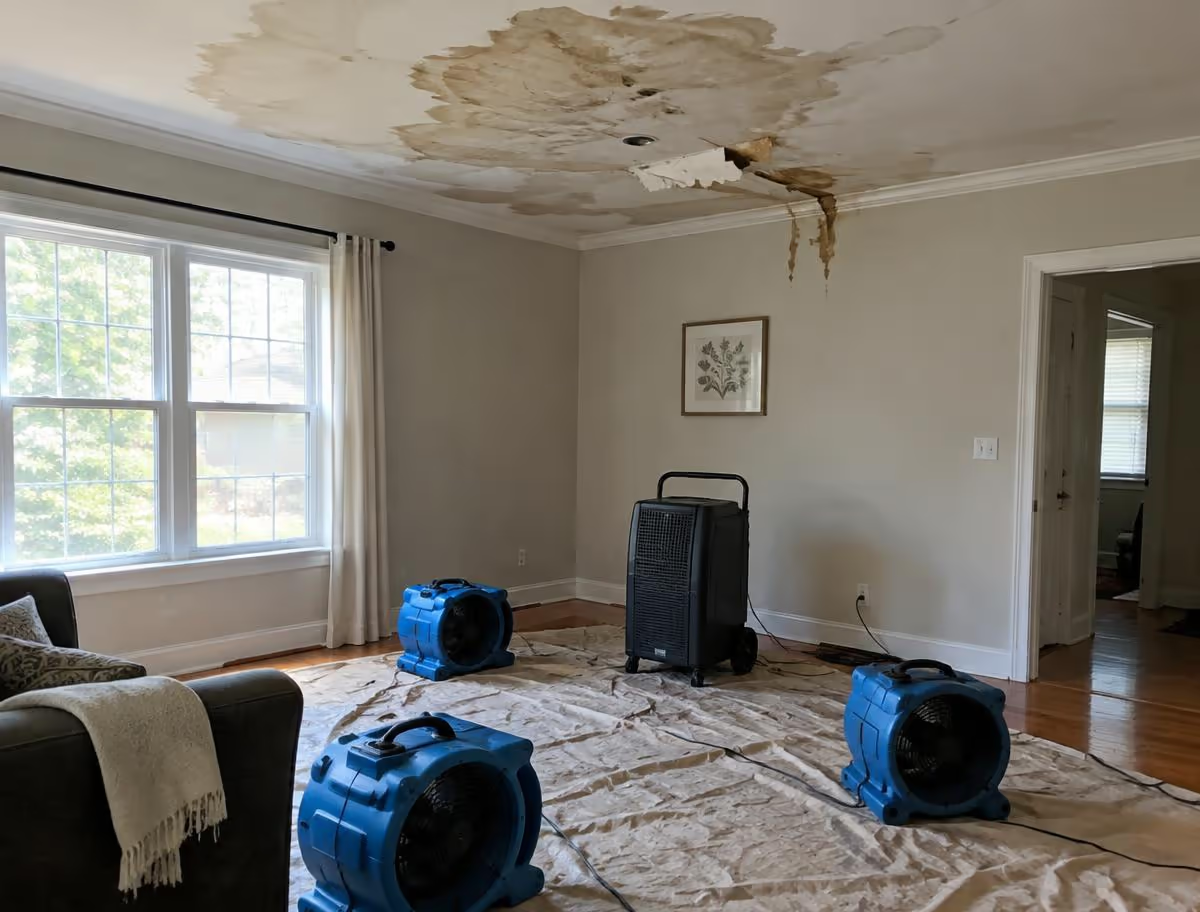
The short answer
DispoKey buys fire-, storm- and water-damaged houses as-is for cash, before or after the insurance claim settles, so owners can move on without managing contractors, permits and a months-long rebuild.
What weighs on you
We hear this every week
Rebuilds take a long time
Contractors, permits and inspections stack up.
Payouts fall short
Deductibles and limits leave gaps.
Ongoing costs
Mortgage and taxes continue on a home you can't use.
Side by side
Your options, honestly compared
Direct sale with DispoKey
- Repairs before sale
- None
- Contractor management
- None
- Time to cash
- As little as 10–14 days
- Insurance claim
- Work around it
Rebuild, then sell
- Repairs before sale
- All of it
- Contractor management
- You
- Time to cash
- Months
- Insurance claim
- You manage it
Sell to a retail buyer
- Repairs before sale
- Usually required for financing
- Contractor management
- Some
- Time to cash
- Hard to finance a damaged home
- Insurance claim
- You manage it
How it works
Four calm steps, at your pace
Tell us what happened
Photos of the damage and your claim status help.
As-is offer
Priced for the house as it is today.
Sort out the claim
Who keeps insurance money is written into the contract.
Close and move on
No rebuild, no contractors.
The short answer
DispoKey buys fire-, storm- and water-damaged houses as-is for cash, before or after the insurance claim settles, so owners can move on without managing contractors, permits and a months-long rebuild.
- 1Tell us what happened
- 2As-is offer
- 3Sort out the claim
- 4Close and move on
Selling with an open insurance claim
You can often sell before the claim is fully settled. The purchase contract should spell out who receives future insurance payments. If your mortgage lender is named on the claim check, they may need to sign off. Your insurance adjuster or a public adjuster can explain the claim side.
Why damaged homes are hard to finance
Most mortgage programs require a home to be safe and habitable. A house with major fire or water damage often won't qualify, which shrinks the pool of retail buyers to cash buyers and renovators. We buy in the current condition — no repairs, cleaning or staging, and you leave behind anything you don't want.
This page is general information, not legal, tax or financial advice. Rules vary by state; for your specific situation, talk with a licensed attorney, tax professional or HUD-approved housing counselor.
Questions homeowners ask
Related situations
See your options today
Free, private and no obligation. You decide what happens next.