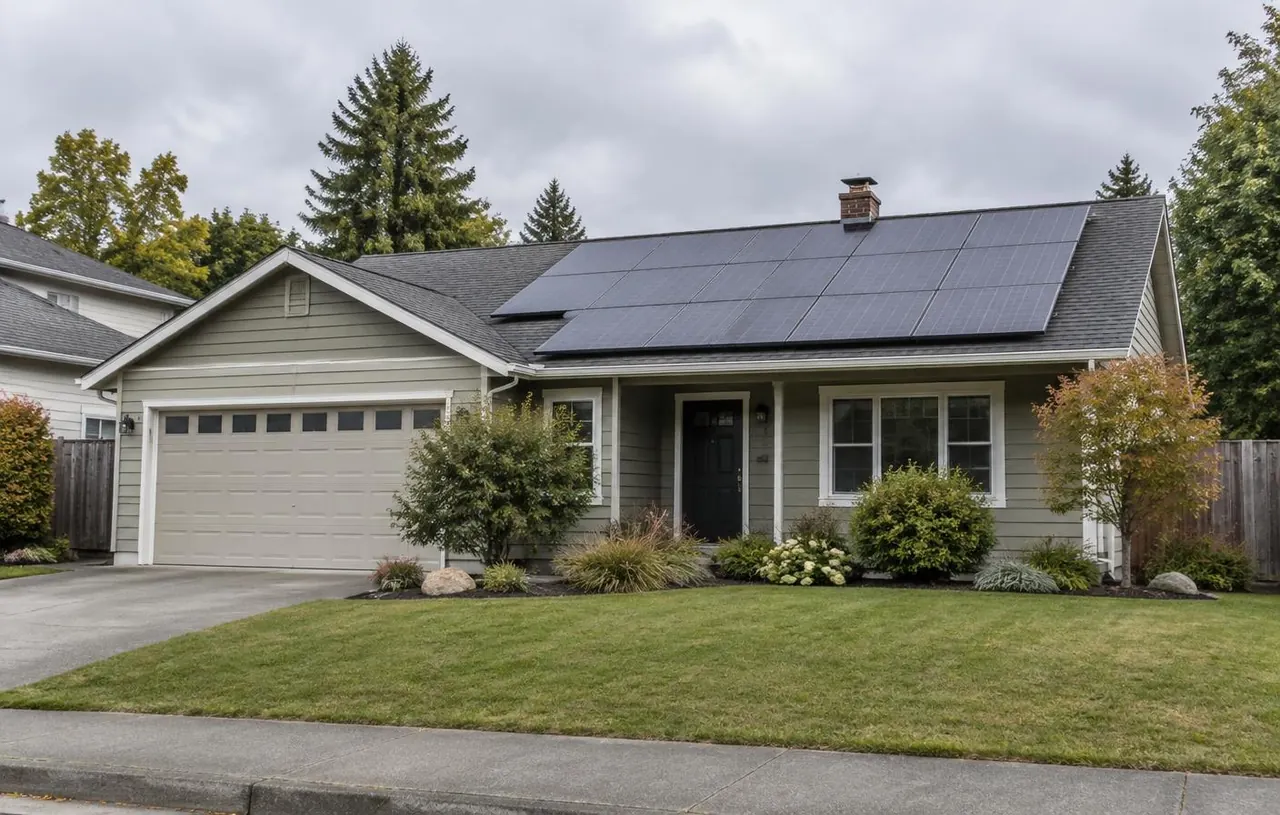
Quick answer: Before selling a house with solar panels, identify who owns the equipment and which agreement remains active. Paid-off panels, a solar loan, a lease and a power purchase agreement need different paperwork. Compare written payoff or transfer terms before estimating proceeds; a roof full of panels does not prove the system is debt-free.
- Find the signed purchase, financing or service agreement.
- Request account-specific payoff or transfer instructions.
- Separate equipment ownership, debt and warranty records.
- Compare proceeds using documented obligations, not a sales estimate.
A solar payment can look like a utility bill while representing a very different obligation. Start with the document behind the payment. This workflow helps a homeowner build a sale-ready solar file without assuming that every system transfers automatically or that every buyer wants the same arrangement. For the wider sale decision, read how to sell a house as is.
Identify the arrangement before choosing a sale route
The Department of Energy distinguishes direct ownership, loans, leases and power purchase agreements. Its homebuyer guide asks buyers to investigate the system's ownership and agreement terms. Those distinctions are the starting point for your file, not interchangeable descriptions of one product. [1]
What should paid-off panel records establish?
Collect the purchase agreement, evidence of completed payments, installer information and available warranty documents. Keep the equipment record separate from statements about energy production. A paid invoice helps explain payment history; it does not by itself answer every question about warranty transfer, roof work or utility arrangements.
Write down what you can demonstrate and what remains unknown. If you inherited the system with the house, look for the prior closing packet and ask the identified provider for copies. Avoid describing panels as fully paid merely because there is no separate monthly bill.
What changes when a solar loan remains?
Identify the current lender or servicer, account holder and signed loan agreement. Request the available payoff process and ask whether any transfer option actually exists for that account. Do not advertise a buyer assumption until the lender's written response supports it. The planning question is which documented route can fit the sale, not which route sounds easiest.
Request three document sets
Create separate folders for ownership, money and operating history. Ownership contains the purchase or service agreement. Money contains recent statements and any dated payoff or transfer quote. Operating history contains installation records, maintenance information, warranty terms and available production reports. Label missing records rather than filling gaps with recollection.
Open the solar sale evidence checklist
- Equipment owner and current account holder identified.
- Signed agreement and amendments located.
- Payoff or transfer request tied to the actual account.
- Quote date, expiration and stated charges recorded.
- Warranty transfer instructions requested separately.
- Open questions sent to the provider or closing team.
Compare a loan payoff with lease or PPA transfer
A lease and a power purchase agreement are not simply unpaid purchase loans. In its financing overview, the CFPB distinguishes ownership financed through a loan from third-party ownership through leases or power purchase agreements. Read the actual agreement rather than importing assumptions from another financing model. [2]
For a lease or PPA, request the provider's sale-related process, any buyer application, stated charges and alternatives offered under the agreement. Keep a transfer request marked pending until the required steps are documented as complete. If a buyout option is offered, obtain its written amount and conditions; do not calculate it by adding remaining monthly payments.
| Starting point | Next step | Outcome |
|---|---|---|
| Identify agreement | Request account terms | Compare documented routes |
| Paid-off equipment | Ownership and warranty file | Buyer information packet |
| Solar loan | Payoff or permitted transfer terms | Proceeds comparison |
| Lease or PPA | Provider's sale process | Written completion evidence |
Compare proceeds with separate solar line items
Keep the home price, mortgage payoff, solar obligation and estimated selling costs on separate lines. Do not subtract the same solar amount twice if it already appears in another closing estimate. If the solar figure is still pending, show a range clearly marked provisional rather than a single confident net number.
The existing date-specific payoff workflow explains why a changing closing date deserves a fresh document check. A mortgage guide does not establish your solar account's terms. Apply the same record discipline while asking the solar provider for its own dated instructions.
Hypothetical example: two offers, one unresolved obligation
Hypothetical example, not a customer result: A homeowner compares a $285,000 offer with a $291,000 offer. Both use an estimated $170,000 mortgage payoff and $9,000 in other costs. The first also assumes a documented $18,000 solar payoff, leaving $88,000 before other adjustments. The second leaves $112,000 before resolving solar. It is not yet a $24,000 advantage: the solar treatment remains unknown.
If the second route later requires the same $18,000 payoff, its comparable estimate becomes $94,000. The difference is $6,000, not $24,000. These invented figures demonstrate comparison only. They do not establish what your provider allows, what a buyer will accept or what the house is worth.
Describe condition without promising extra value
Provide installation age, inverter details and available maintenance history. The Department of Energy's guide specifically raises system age, inverter type and roof condition as useful buyer questions. You can answer those questions with records without promising a particular energy saving or sale-price premium. [1]
Fannie Mae's appraisal guidance treats solar arrangements differently: leased or PPA panels are not included in appraised value under the cited guidance, while owned and financed arrangements have distinct criteria. That is program-specific appraisal guidance, not a universal valuation rule for every sale. It supports one practical point: describe ownership accurately rather than claiming all panels add the same value. [3]
When DispoKey may not be your best option
If maximizing open-market exposure matters more than convenience and you can manage the provider's documentation process, a traditional listing may fit better. If you prefer to compare a cash route, use DispoKey's seller inquiry and share the known arrangement with your Seller Success Manager. Close in as little as 21 days, subject to the transaction; unresolved solar paperwork can affect timing.
Key takeaways
Identify the agreement first, obtain written account terms and separate solar costs from other sale costs. Keep unsupported transfer assumptions out of your offer comparison. A useful solar file tells a buyer what is known and shows the exact unresolved items without promising automatic approval, guaranteed savings or a higher price.
Frequently asked questions
Can I sell before my solar loan is paid off?
Start by obtaining the lender’s written payoff and any permitted transfer process. A remaining balance identifies a question to resolve, not a universal prohibition or an automatic right to transfer the debt.
Are leased panels the same as paid-off panels?
No. Third-party ownership under a lease or power purchase agreement requires reviewing that agreement. Paid-off equipment needs ownership and warranty records; a lease or PPA also needs the provider’s sale-related process.
Does a clean home title search answer every solar question?
No. Keep the signed solar agreement and account response in the file alongside closing records. Ownership, financing, warranty and operating arrangements answer different questions; do not replace missing provider documents with an assumption.
References
- A Consumer’s Guide to Buying a House with Solar Panels — Department of Energy.
- Issue Spotlight: Solar Financing — CFPB.
- Appraising properties with solar panels — Fannie Mae.