Quick answer: If your mortgage payoff quote expired before closing, request a revised statement for the actual payoff date through your servicer and closing professional. DispoKey recommends checking three items before relying on estimated proceeds: the date, the itemized amount and the authorized delivery instructions. Your monthly balance is not a substitute.
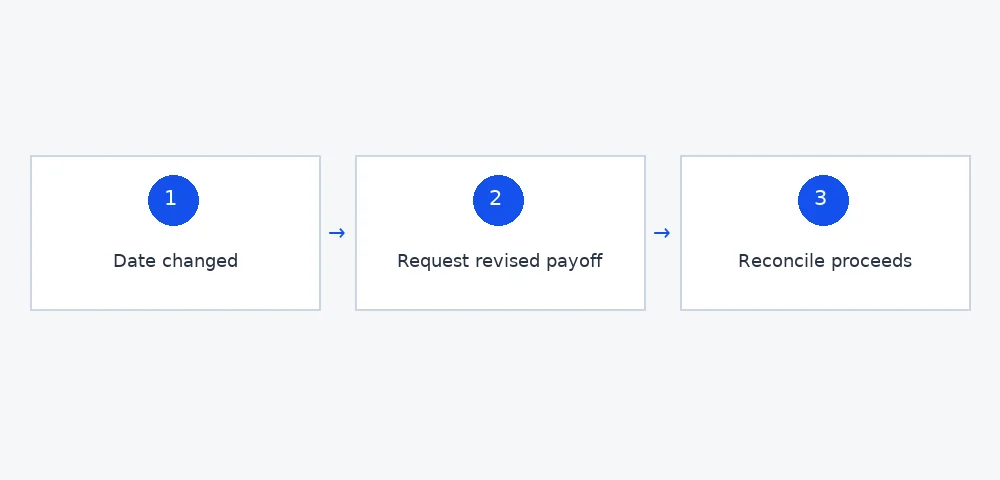
- Confirm the revised closing date in writing.
- Request a payoff statement covering the intended payment date.
- Reconcile proceeds before approving the final closing figures.
A postponed closing affects more than moving arrangements. The mortgage payoff may have been prepared for the original date, while interest and other charges continue according to the loan. This guide addresses that specific exception: a sale is already moving forward, but its payoff paperwork no longer matches its timing. For the basic definition, use the payoff letter glossary rather than treating this workflow as a replacement.
Identify the payoff-date mismatch first
Compare the date covered by the current payoff statement with the date funds are expected to reach the servicer. The signing date and the payment arrival date may not be identical.
Ask your closing professional which date they need the statement to cover. Do not merely add a few days to a figure yourself and assume it is authorized. Save the original statement, label it superseded when a replacement arrives and keep the changed closing agreement alongside it. If the date is still uncertain, explain that uncertainty to the servicer instead of submitting a request built around a date nobody has agreed to.
Is my mortgage balance the same as my payoff amount?
No. The payoff amount can include interest through the intended payoff date and unpaid fees, so the current balance alone may understate what is required. The official consumer explanation makes that distinction directly. [1]
A monthly mortgage statement helps identify your account and servicer, but it is not automatically a payoff authorization. A recent payment may also need to be reflected in the revised figure. Ask how pending transactions are treated. Keep screenshots as supporting records, not as a replacement for the date-specific document your closing professional needs.
Request a revised payoff with a short checklist
Provide the account-identification and authorization information the servicer requires, the intended payoff date and the permitted delivery destination. Ask the closing professional to coordinate the request when appropriate.
Open the changed-closing-date checklist
- What is the revised signing date?
- When should the payoff funds arrive?
- Who is authorized to request the statement?
- Where will the replacement be delivered securely?
- Who will confirm the closing figures were updated?
Keep a dated request record and a named point of contact. The federal servicing resources describe responsibilities, but they do not make every request channel or exception identical. [2][3] Avoid treating a general information-request deadline as a guaranteed closing timetable. If you are told the statement cannot arrive in time, raise that issue with the closing professional immediately; silence is not approval to use an expired amount.
| Check | Responsible conversation | Record to retain |
|---|---|---|
| Date changed | Buyer and closing professional | Revised date agreement |
| Payoff revised | Mortgage servicer | Date-specific statement |
| Proceeds reconciled | Closing professional | Updated closing figures |
A worked delay example without guessing the payoff
A simple estimate can show why a delay matters, but only the servicer's revised statement establishes the requested amount. These figures are invented examples, not loan terms or an offer.
Suppose the earlier payoff quote was $182,400 and its stated daily interest was $28. A five-day shift would suggest $140 of additional interest: $28 × 5. That arithmetic is a planning estimate, not permission to send $182,540. A posted payment, allowed fee or different receipt date could change the actual statement. Have the closing professional use the replacement document rather than treating the estimate as final.
Suppose your projected proceeds before the delay were $37,000. Subtract the illustrative $140 and $350 of additional agreed holding expenses: the planning figure becomes $36,510. Separate loan-related changes from moving or accommodation costs. Otherwise the same expense can appear twice. Check each final amount against the appropriate document and make clear which figures remain estimates.
Reconcile the final closing figures line by line
The replacement payoff should flow into the final proceeds calculation, not remain in an email while the original figure stays on the closing paperwork. Ask for an updated explanation of anything that changed.
Compare the sale price, mortgage payoff, agreed seller costs, tax adjustments and other deductions. A higher payoff does not automatically mean the buyer changed the offer. Conversely, unchanged loan principal does not prove the overall proceeds stayed constant. Ask which document supports each revision. If a charge is unfamiliar, request an itemized explanation before approving it, rather than assuming every difference is daily interest.
What if I made a mortgage payment while closing was delayed?
Tell the servicer and closing professional about the payment and ask whether it has posted and been included. Do not subtract it yourself from an earlier quote.
Keep the payment confirmation, but recognize that processing and application details belong with the servicer. Continue following your existing payment obligations unless an authorized arrangement changes them. A planned sale is not, by itself, an instruction to stop paying. If you think the statement is incorrect, preserve the request and response records and seek qualified help rather than improvising a wire amount.
Keep payoff delivery and payment verification secure
Use independently established contact channels for sensitive documents and payment instructions. A correct payoff figure does not establish that an unexpected account-change message is authentic.
Share account information only with authorized parties through their accepted secure process. Avoid forwarding full statements to unrelated recipients. Ask the closing professional how they verify receipt and handle changed instructions. Save records privately; a public sale listing does not need your mortgage account number. When instructions change unexpectedly, pause the payment conversation and confirm through a contact method already known to be genuine.
When DispoKey may not be your best option
If your move-in-ready home is already under a sound contract and only the payoff date needs updating, changing sale routes may create more disruption. Work through the existing closing first.
If the current sale falls apart and you want to compare alternatives, review home-selling options and the cash-offer request. A Seller Success Manager can discuss your timing; close in as little as 21 days, subject to the transaction. Compare that option with listing, not with an assumed guaranteed date. Related preparation appears in selling during probate and selling a water-damaged home.
Who confirms the payoff was received after closing?
Ask the closing professional which receipt or confirmation they obtain from the servicer. Sending funds and confirming their application are separate records.
Keep the final statement and the closing record together. If the amount or application is disputed later, that packet helps identify the date, authorized figure and payment actually used. Do not assume a signed closing document alone proves the mortgage account has been updated.
Key takeaways
Match the payoff to the actual payment date, distinguish it from the monthly balance and reconcile every changed proceeds figure. Preserve both versions so the closing professional can see which one is current. This is educational guidance, not loan servicing or legal advice; payoff disputes and contract changes need qualified review.