Quick answer: House hacking means buying a 2–4 unit property, living in one unit and renting the others so rent covers much of the mortgage. FHA loans allow as little as 3.5% down for owner-occupants who meet credit rules. It is a Buy & Hold strategy; once you move out, DispoKey's approved buyers can source the next rental off-market.
- Owner-occupied loans need you to move in and live there.
- Test the deal with rent from the other units only.
- Plan for vacancy, repairs and being your tenants' neighbor.
What is house hacking?
House hacking is owning the home you live in while it earns rent. The classic version is a duplex, triplex or fourplex where you live in one unit and lease the rest.
Variations include renting spare bedrooms in a single-family house or renting a legal accessory dwelling unit. The idea is the same: other people's rent offsets your housing cost while you build equity and landlord experience. It is a Buy & Hold strategy, and many investors use it to buy their first rental.
Which loans work for house hacking?
Owner-occupied loans are the main advantage, because they often need less down payment than investment loans. Each program has occupancy and property rules.
FHA loans
HUD says FHA-insured loans can be used for one to four units when you live in one of them. Borrowers with a credit score of 580 or higher may put down as little as 3.5%. For three- and four-unit properties, FHA also applies a self-sufficiency test that compares expected rent with the mortgage payment.
VA and conventional loans
VA home loans let eligible service members and veterans buy up to four units if they live in one. Conventional owner-occupied loans also allow multi-unit purchases, with down payments that vary by lender and unit count.
Occupancy rules
Owner-occupied programs require you to move in within a set time and live there as your main home. Saying you will live there when you will not is mortgage fraud.
How to tell if a house hack works
Judge the deal on the rent from the units you will not live in. If that rent covers most of the full housing payment, your own cost of living drops.
Price rents from nearby listings and HUD Fair Market Rents; our guide on how much rent you can charge shows how. Then subtract vacancy, repairs, capital reserves and any utilities you pay. A house hack that only works with zero vacancy is not a good deal.
The FHA self-sufficiency test for three and four units
For three- and four-unit properties, FHA checks whether the property's net rental income can cover the full mortgage payment, using the appraiser's market rent estimate rather than your own projection. A fourplex in an area with modest rents may fail the test even if the purchase looks good to you, so ask your lender to run it before you write an offer.
Budget for big-ticket repairs
Multi-unit buildings have more roofs, water heaters and kitchens per lot than a single-family home. Set aside money monthly for these, and inspect them before you buy with our rental inspection checklist.
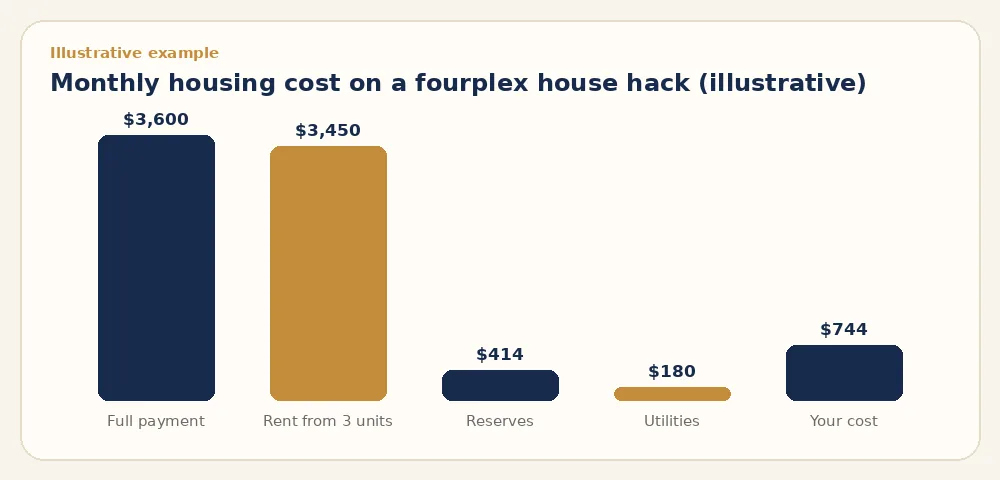
| Monthly line (illustrative fourplex example) | Amount |
|---|---|
| Full housing payment (loan, taxes, insurance, FHA premium) | $3,600 |
| Rent from three other units | +$3,450 |
| Vacancy and repair reserve (12%) | -$414 |
| Owner-paid utilities | -$180 |
| Your net monthly housing cost | $744 |
What it is like to be a live-in landlord
You are both landlord and neighbor. That makes repairs fast and screening personal, but it also means less privacy and quick tenant requests.
Screen every applicant the same way and follow fair housing law; HUD explains the protected classes. Our guide to how to screen tenants covers applications and criteria. Use a written lease, keep security deposits by your state's rules and document the unit's condition at move-in.
How taxes work on a house hack
The IRS treats the rented part as a rental and the part you live in as your home. You report rent and split expenses between the two.
IRS Publication 527 explains how to divide shared costs such as mortgage interest, taxes and insurance, and how to depreciate only the rented portion. See our rental property depreciation guide for the 27.5-year schedule. Keep records by unit from day one, including receipts that apply only to the rented units.
What to do after you move out
Once your occupancy requirement is met, you can move and rent all units, keeping the original loan. Many investors then buy the next property as a pure rental.
For that next step, DispoKey's marketplace lists off-market Buy & Hold and Fix & Flip properties for approved cash buyers; access requires team approval. Apply to join and set your market and price range.
When DispoKey may not be your best option
Our marketplace is for investors buying with cash or their own financing, not for owner-occupant loans with long contingencies. If you are buying your first house hack with FHA or VA financing, a lender and a buyer's agent will serve you better. Come back when you are ready for a cash or investor-financed rental.
Key takeaways
- House hacking pairs owner-occupied financing with rental income.
- FHA allows 3.5% down on 1–4 units for qualifying owner-occupants.
- Underwrite with reserves; do not rely on zero vacancy.
- Taxes split between your home and the rented portion.
Frequently asked questions
Is house hacking a good idea for beginners?
It can be, because owner-occupied loans lower the entry cost and you learn landlording up close. Run the numbers with reserves first.
Can I house hack with an FHA loan?
Yes. HUD allows FHA loans on one to four units when you live in one, with 3.5% down at a 580 credit score or higher.
How long do I have to live in a house hack?
Occupancy terms depend on the loan program. Owner-occupied loans generally require it to be your main home after closing.
Do I pay tax on house hacking rent?
Yes. Rent is income, but you can deduct the rented portion's expenses and depreciation under IRS Publication 527.