Quick answer: The BRRRR method means buying a property below its value, rehabbing it, renting it, refinancing based on the new value, and repeating with the cash you pull out. It is a Buy & Hold strategy. Lenders often require months of ownership before a cash-out refinance; Fannie Mae generally requires 6 months. DispoKey's marketplace lists off-market deals for approved buyers.
- Buy far enough below after-repair value to leave room for the refinance.
- Budget the rehab and the months you will hold it.
- Confirm refinance rules with your lender before you buy.
What is the BRRRR method?
BRRRR stands for buy, rehab, rent, refinance, repeat. You buy a property that needs work at a discount, fix it, place a tenant, then refinance into a long-term loan based on the higher value. If the new loan is large enough, it repays much of the cash you put in, which you use on the next property.
At DispoKey, BRRRR sits under the Buy & Hold strategy because the goal is a long-term rental. It works best for investors with cash or short-term financing, a reliable contractor and patience for each step.
Step 1: Buy below value
The deal is made at purchase. Start from the after-repair value (ARV), subtract your rehab budget and costs, and decide the most you can pay while leaving equity for the refinance. Our guide on how to calculate ARV shows how to support the value with real sales.
Off-market properties often offer the discount BRRRR needs because sellers value speed or an as-is sale. Many investors fund the purchase with cash or hard money.
Step 2: Rehab for renters
Rehab for durability and rentability, not for luxury. Focus on safety, systems, kitchens, baths and finishes that survive tenants.
- Get written scopes and bids before closing.
- Add a contingency for surprises behind walls.
- Pull permits where required, because appraisers and lenders may ask.
- Track every receipt; you will need them for taxes and the refinance file.
Step 3: Rent it to a qualified tenant
A signed lease at market rent supports the refinance, since many lenders look at rental income. Screen consistently and follow fair housing rules; our guide on how to screen tenants covers the steps. Check what similar homes rent for and confirm the numbers with HUD Fair Market Rents and local listings.
Step 4: Refinance and the seasoning rule
Seasoning is the time you must own a property before a lender will base a cash-out loan on its new value. Fannie Mae's Selling Guide generally requires at least six months between purchase and a cash-out refinance, with a delayed financing exception for some cash purchases. Many DSCR and portfolio lenders set their own rules.
Ask lenders before you buy: the waiting period, the maximum loan-to-value, whether they use the appraised value or your cost, and how they treat rehab spending. Our guide on delayed financing explains the exception.
Worked example: how much cash comes back
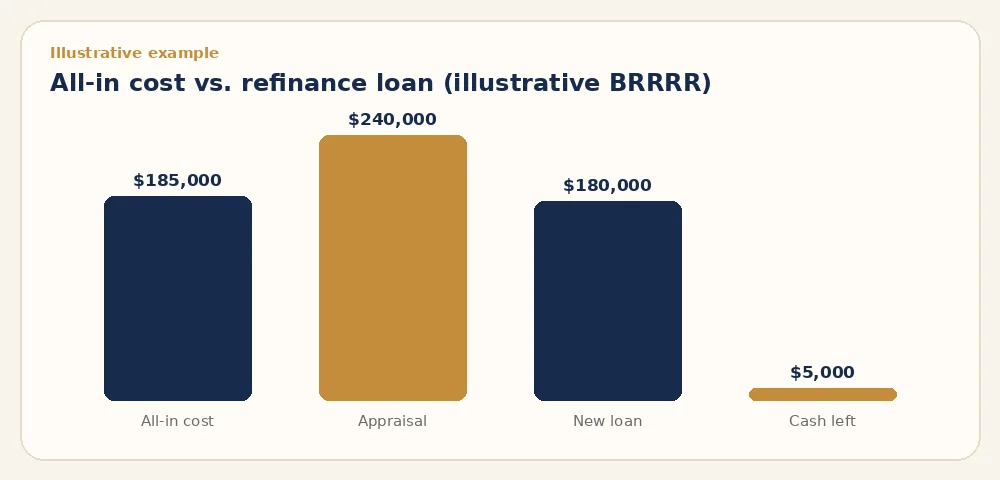
Track all-in cost and the new loan amount. The difference is cash left in the deal.
In the illustrative example in this guide, the investor's all-in cost is $185,000 and a 75% loan on a $240,000 appraisal returns $180,000, leaving $5,000 in the property. If the appraisal comes in lower, more cash stays in, so stress test the value.
| Line (illustrative BRRRR example) | Amount |
|---|---|
| Purchase price | $130,000 |
| Rehab | $42,000 |
| Closing and holding costs | $13,000 |
| All-in cost | $185,000 |
| Appraised value after rehab | $240,000 |
| Cash-out loan at 75% | $180,000 |
| Cash left in the deal | $5,000 |
BRRRR vs. a fix and flip
Both start with a discounted purchase and a rehab, but the exit is different. A flip sells the improved property and takes profit as a lump sum, taxed in the year of sale. BRRRR keeps the property, takes the equity out as loan proceeds and earns monthly rent.
BRRRR depends on rents covering the new, larger loan payment, taxes, insurance and reserves. If the numbers only work as a sale, flip it; if rent supports the refinance and you want long-term income, BRRRR may fit. Compare both with our cash-on-cash return guide.
What are the risks of BRRRR?
The main risks are rehab overruns, a low appraisal, slow lease-up and rate changes before you refinance. Any of these can leave more money in the deal than planned.
Keep reserves, refinance only when cash flow still works at the new payment, and review the plan in our cash flow guide. Depreciation and repairs are covered in rental property depreciation.
Questions to ask a refinance lender before you buy
- How long must I own the property before a cash-out refinance?
- What is the maximum loan-to-value on a cash-out?
- Will you use the new appraised value or my purchase cost?
- Do you require a signed lease, and how do you count rent?
- What credit, reserve and debt-service coverage ratio do you require?
Get answers in writing. Rules change, and different lenders treat the same deal very differently.
Finding BRRRR deals through DispoKey
DispoKey's marketplace lists off-market Buy & Hold and Fix & Flip properties for approved cash buyers. Access requires team approval, and every deal needs your own review. Apply as a buyer to see properties in your markets.
When DispoKey may not be your best option
If you need a long financing contingency or a move-in-ready rental, a listed property may fit better. Our deals suit buyers who can close with cash or short-term financing and manage a rehab.
Key takeaways
- BRRRR is a Buy & Hold strategy built around a refinance.
- Profit is set at purchase; buy far enough below ARV.
- Fannie Mae generally requires 6 months before a cash-out refinance.
- Stress test the appraisal and keep reserves.
Frequently asked questions
What does BRRRR stand for?
Buy, rehab, rent, refinance, repeat.
How long do you have to wait to refinance a BRRRR property?
Lenders set seasoning rules. Fannie Mae generally requires 6 months, with a delayed financing exception for some cash purchases.
Is BRRRR a Fix & Flip strategy?
No. At DispoKey, BRRRR is treated as Buy & Hold because you keep the property as a rental.
What is the biggest BRRRR risk?
A low appraisal or rehab overrun that leaves more cash in the deal than planned.