Quick answer: To qualify for a DSCR loan, the property's rent has to cover its monthly payment: rent ÷ PITIA (principal, interest, taxes, insurance, HOA). Lenders set their own minimum ratio, down payment, credit score and reserve rules, so get each one's guideline in writing. DispoKey's approved buyers use deal numbers to test DSCR before they offer.
- Calculate DSCR from market rent and full PITIA, not principal and interest alone.
- Document rent with a lease or an appraiser's rent estimate.
- Ask each lender for its minimum DSCR, down payment, credit and reserve rules.
- Stress-test the ratio at a higher rate and lower rent.
A DSCR loan qualifies the rental, not your W-2. That is why buy-and-hold investors use it when tax returns show heavy depreciation or self-employment income. It is also why a deal that looks fine on paper can fail underwriting: the lender's rent number, tax figure or insurance quote is lower or higher than yours. This guide covers the formula, the documents, a worked example with labeled numbers, and how to fix a ratio that comes in short. For the plain definition, see our DSCR loan glossary entry.
How is DSCR calculated for a rental loan?
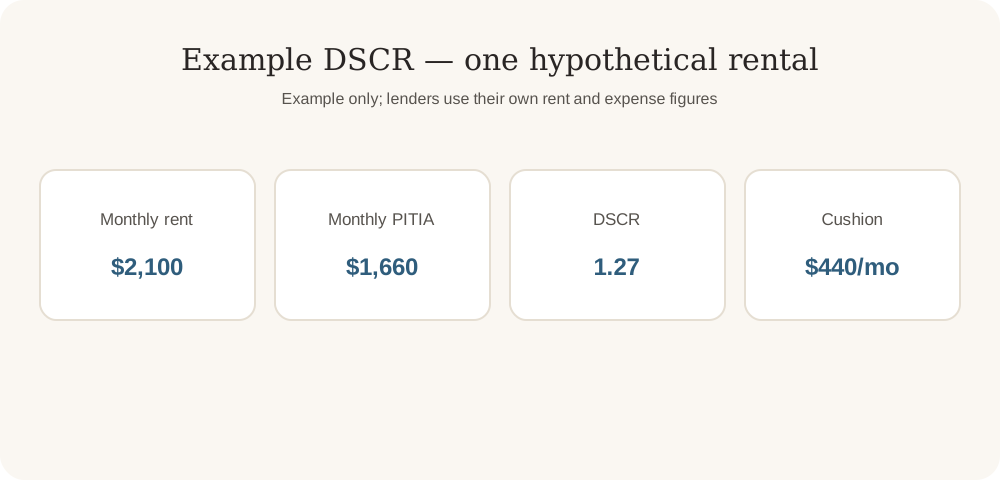
DSCR equals the property's monthly rent divided by its monthly PITIA. A ratio of 1.00 means rent exactly covers the payment; above 1.00 leaves a cushion.
PITIA includes principal, interest, property taxes, hazard insurance and any HOA dues. Many first-time borrowers leave out taxes or insurance and overestimate the ratio. Pull the current tax bill from the county and get a real insurance quote before you rely on the number.
| Example input | Monthly amount |
|---|---|
| Market rent (example) | $2,100 |
| Principal + interest (example) | $1,280 |
| Property taxes (example) | $260 |
| Insurance (example) | $120 |
| HOA | $0 |
| PITIA total | $1,660 |
| DSCR = $2,100 ÷ $1,660 | 1.27 |
What DSCR do lenders require?
There is no single national minimum. Each lender sets its own threshold and may price the loan differently above and below it.
Some lenders accept ratios near 1.00 with stricter terms, and some lend below 1.00 with a larger down payment. Treat any number you hear secondhand as a starting question, not a rule. Ask for the written guideline, and ask how the rate changes at different ratios.
What are the DSCR loan requirements beyond the ratio?
Expect four other checks: down payment, credit, cash reserves and the property itself. The ratio gets you in the door; these decide the terms.
- Down payment: usually larger than an owner-occupied loan. Ask the lender for its maximum loan-to-value by property type.
- Credit score: lenders set minimums and price by tier.
- Reserves: months of PITIA held in the bank after closing.
- Property: an appraisal, sometimes with a rent schedule, and a property type the lender accepts.
- Entity: many DSCR lenders allow an LLC borrower with a personal guarantee.
Does a DSCR loan require an appraisal?
Generally yes. The appraisal confirms value for the loan-to-value limit and often supplies the market rent estimate the lender uses in the ratio.
If the appraiser's rent is lower than your lease or your estimate, the lender typically uses the appraiser's figure. Check rents yourself first: HUD publishes Fair Market Rents by metro area, which give a public benchmark for whether your rent assumption is reasonable. [1]
How to get a DSCR loan, step by step
Run your own numbers, then let lenders compete on the same file.
Open the DSCR application checklist
- Underwrite the rent. Use the signed lease or comparable rentals, then sanity-check against HUD Fair Market Rents.
- Price full PITIA. County tax bill, insurance quote and HOA statement.
- Calculate DSCR at two rates. The quoted rate and one point higher.
- Gather documents. ID, entity documents, bank statements for reserves, purchase contract and lease.
- Request written terms from two or three lenders. Compare rate, points, prepayment terms and reserves.
For the full rental model, pair this with our rental property cash flow analysis and the investor calculators.
Is a passing DSCR the same as positive cash flow?
No. DSCR ignores vacancy, repairs, capital expenses and management, so a property can pass at 1.10 and still lose money in a bad year.
Budget those costs separately. Our vacancy rate and cash-on-cash return entries explain the measures lenders skip. For taxes, IRS Publication 527 explains how rental income and expenses are reported, and Schedule E is where most individual landlords report them. [2] [3] Depreciation that lowers your taxable income is one reason investors choose DSCR qualification over income-based loans.
How to fix a DSCR that comes in too low
Raise the rent side, lower the payment side, or walk away. There are only three levers.
- Larger down payment: lowers principal and interest.
- Buy down the rate: points lower the payment; compare the cost to the savings.
- Shop insurance: a lower premium raises the ratio immediately.
- Negotiate the price: the cleanest fix, and the one that protects your cash flow.
If you buy with cash and refinance later, delayed financing and the broader buy and hold strategy explain how the DSCR loan fits that plan.
When DispoKey may not be your best option
If you need a financing contingency or a long closing window to shop loans, off-market deals may not suit you. Sellers on these deals usually expect a firm buyer and a fixed timeline, so have your lender's terms before you offer.
Find rentals that pass DispoKey's numbers
Approved buyers see off-market Buy & Hold and Fix & Flip deals with the figures you need to test DSCR. Access requires team approval. Apply as a buyer, or set up deal alerts in your market.
Key takeaways
- DSCR = monthly rent ÷ full PITIA.
- Lenders set their own minimum ratio, down payment, credit and reserve rules.
- The appraiser's rent estimate often controls the ratio.
- A passing DSCR does not guarantee cash flow; budget vacancy and repairs.
Frequently asked questions
How do you qualify for a DSCR loan?
Show that the property's rent covers its full monthly payment at the lender's minimum ratio, and meet its down payment, credit score and reserve rules.
Do DSCR loans check your income?
They generally qualify the property's rent instead of your personal income, though lenders still review credit, assets and reserves.
Can you get a DSCR loan with a ratio below 1?
Some lenders offer it, usually with a larger down payment or higher rate. Ask for the written terms.
Can an LLC get a DSCR loan?
Many DSCR lenders lend to LLCs, typically with a personal guarantee from the members.